
Rwanda Tops Africa Visa Openness as Kenya, Ghana and Others Expand Cross-Border Tourism Access
-
Blogs, Immigration, Wellness, Travel
-
-
8 mins
-
Travel and Tour World
-
Ankita Neogi Khan
-


Africa visa divide reveals how Rwanda, Kenya and others are reshaping tourism, aviation and cross-border mobility.
Africa’s tourism market is expanding, yet cross-border movement remains uneven. The latest Africa Visa Openness Index shows only 28.2% of intra-African travel scenarios were visa-free in 2025, although that was the highest share recorded since the index began. At the same time, 51.1% of travel scenarios still required a visa before departure, exposing a persistent gap between continental tourism ambitions and practical mobility. Rwanda and Kenya sit near the open end of the spectrum, while Seychelles, Nigeria, South Africa and Morocco demonstrate very different approaches. The divide matters because visa rules now intersect with air connectivity, tourism receipts, regional integration and traveller costs across Africa.
Africa’s Border Rules Tell Different Stories
The 2025 Africa Visa Openness Index provides the clearest starting point for understanding the continent’s fragmented travel environment. The African Development Bank and African Union Commission have tracked these policies for a decade, measuring what African nationals face when travelling between African countries. A score of 1 is awarded for visa-free access, 0.8 for visa-on-arrival access and zero when travellers need advance authorisation.
The latest edition records 814 visa-free country-to-country travel scenarios, compared with 803 in 2024. That represents 28.2% of intra-African scenarios, compared with 20% in 2016. Meanwhile, 31 African countries offered e-Visas to African travellers in 2025, compared with only nine in 2016.
| Country | 2025 AVOI score | Rank | Key mobility characteristic |
|---|---|---|---|
| Rwanda | 1.000 | 1 | Visa-free access for all Africans |
| Kenya | 0.962 | 3 | Broad exemption from advance travel authorisation |
| Ghana | 0.868 | 5 | Highly open intra-African regime |
| South Africa | 0.377 | 25 | Significant regional tourism dependence |
| Nigeria | 0.321 | 32 | More restrictive advance-visa environment |
| Morocco | 0.151 | 44 | Strong tourism performance despite low AVOI |
| Seychelles | 0.000 | 54 | ETA treatment sharply affects index position |
Rwanda and The Gambia retained the joint top position, while Kenya became the continent’s third-most open country. Ghana remained fifth, giving West Africa a prominent place among Africa’s most accessible travel markets.
Rwanda Shows What Openness Can Unlock
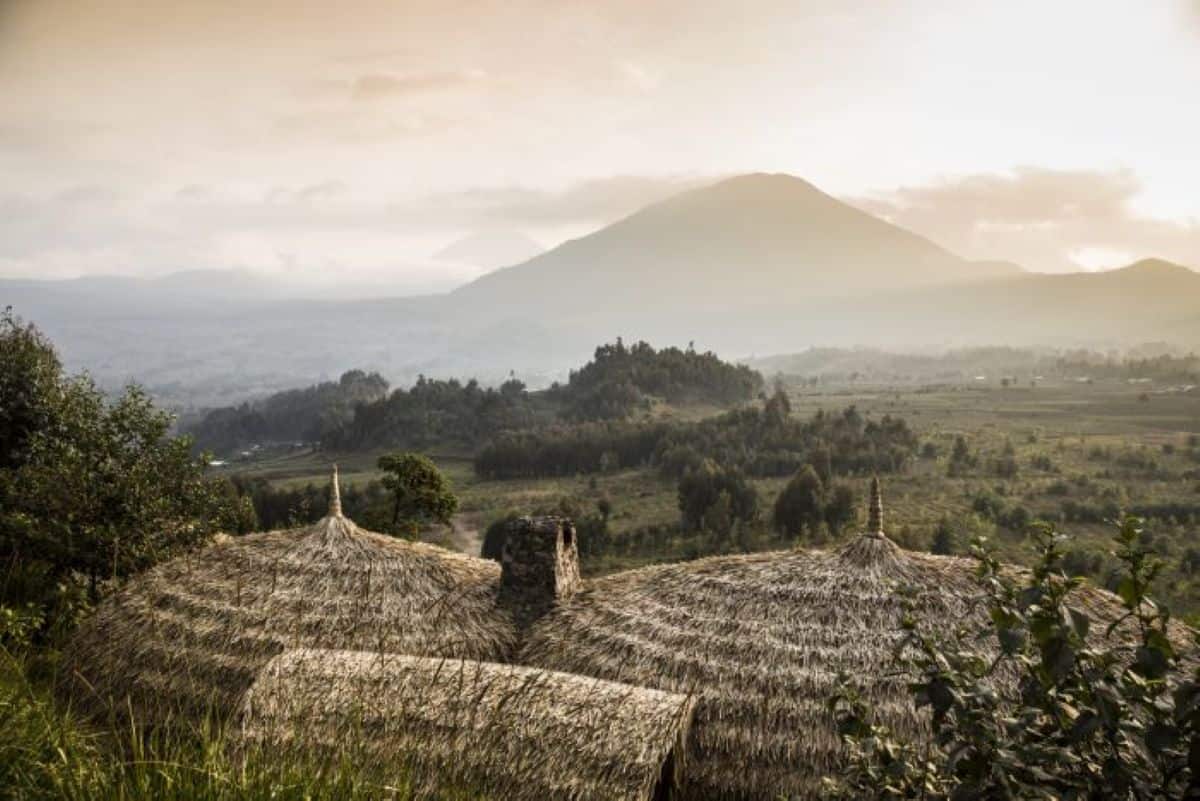
Rwanda provides the clearest example of a country combining exceptionally open entry rules with a growing tourism economy. The country allows visa-free access to citizens of all African countries, giving it the maximum AVOI score of 1.000.
The economic data add another dimension. Rwanda’s National Institute of Statistics reported $579.5 million in travel-service exports during 2024, while travel-service imports reached $363.8 million. The resulting travel-services surplus stood at $215.6 million.
Rwanda’s visitor economy also extends beyond leisure tourism. Its official travel survey tracks business, education, health, holiday, transit and visiting-friends-and-relatives travel. In the fourth quarter of 2024, Rwanda recorded 76,438 non-resident arrivals by air and 248,646 by land.
The figures do not establish that visa openness caused these results. They do, however, show why mobility policy matters to destinations seeking business travellers, regional visitors and longer-stay tourism.
Kenya Moves Quickly Towards Easier Entry
Kenya has emerged as another important case because its policy changed substantially within a short period. The 2025 AVOI records Kenya at 0.962, placing it third across Africa. The index attributes the rise to changes in its electronic travel authorisation system, which exempted citizens of 52 African countries from those procedures.
The tourism numbers provide useful context. Kenya welcomed approximately 2.4 million international visitors in 2024, up 15% from the previous year. Tourism earnings reached KES452.2 billion, representing growth of 19.79% over 2023.
Kenya’s subsequent government planning documents set an even larger ambition. The draft National Tourism Strategy targets five million international arrivals and KES1.2 trillion in tourism revenue by 2030. It also identifies improved infrastructure, product diversification and stronger market access as part of the growth strategy.
This creates an important travel-industry distinction. Removing an entry barrier can improve the conditions for demand, but airlines, accommodation capacity and destination marketing still determine whether that potential becomes actual travel.
Ghana Strengthens The West African Picture
Ghana adds an important ECOWAS perspective to the comparison. Its 2025 AVOI score of 0.868 placed it fifth, positioning the country among Africa’s most open destinations for continental travellers.
The Ghana example also demonstrates why bilateral agreements can matter alongside continent-wide policies. South African government data show that Ghanaian arrivals to South Africa increased 149% in 2024, reaching 36,656 visitors. Officials attributed the rise partly to increased airlift and a visa waiver introduced between the two countries in November 2023.
That episode offers a valuable lesson for travellers and tourism businesses. Visa liberalisation becomes considerably more useful when airlines add capacity at the same time, because legal access alone cannot create a convenient journey.
Seychelles Exposes The ETA Paradox
Seychelles produces perhaps the most revealing statistical twist in the comparison. The island destination received an AVOI score of zero in 2025, despite its longstanding reputation for open entry arrangements. The reason lies in the index’s treatment of its compulsory electronic travel authorisation.
The distinction is important for travellers. A visa, an e-Visa and an ETA may involve different administrative systems, yet all can create a pre-departure requirement. Under the AVOI methodology, advance authorisation does not receive the same score as genuinely visa-free movement.
For consumers, that means checking the exact entry procedure rather than relying on the phrase “visa-free”. A traveller should verify whether an online authorisation, passport registration, health declaration or other pre-travel form remains mandatory.
Nigeria Highlights A Different Mobility Model
Nigeria’s position is markedly different. Its 2025 AVOI score stood at 0.321, ranking it 32nd among African countries. That places one of the continent’s largest travel markets considerably below Rwanda, Kenya and Ghana on the index.
The index also records a wider policy movement towards advance requirements in Nigeria. During 2025, 20 African countries changed policies affecting nationals from at least one other African country. Eleven improved their scores, while nine recorded lower scores.
The Nigerian case therefore matters beyond tourism. Entry policy affects business travel, family mobility, conferences, regional commerce and airline demand. For a large population centre, even small changes in border procedures can have implications for the wider travel ecosystem.
South Africa Depends Heavily On Regional Visitors
South Africa presents a particularly useful counterpoint to the openness argument. Its 2025 AVOI score was 0.377, ranking 25th, yet the country welcomed 8.92 million tourists in 2024. Most strikingly, 76% of those arrivals came from the rest of Africa.
Official tourism data put African arrivals at about 6.8 million visitors in 2024. Zimbabwe alone supplied 2.18 million arrivals, while Mozambique contributed 1.59 million and Lesotho 974,000.
The Ghana example is even more instructive. South African authorities linked the 149% increase in Ghanaian visitors to the 2023 visa waiver, combined with greater airlift and targeted destination marketing. The evidence demonstrates how visa policy, aviation capacity and tourism promotion can reinforce each other.
Morocco Proves Tourism Has Multiple Engines
Morocco offers another striking contrast. Its AVOI score was only 0.151, ranking it 44th, yet its tourism sector has expanded rapidly. The country’s tourism ministry reports 17.4 million tourist arrivals in 2024, representing a 20% increase over 2023 and 35% above 2019.
Tourism revenue reached MAD112 billion in 2024, while overnight stays rose to 28.7 million. The visitor mix was also unusually balanced, with international tourists accounting for 51% and Moroccans residing abroad representing 49%.
The momentum continued into 2025. Morocco recorded 19.8 million tourist arrivals, up 14% from 2024, while tourism receipts reached MAD124 billion by the end of November.
Morocco therefore demonstrates why visa openness should not be treated as a standalone tourism predictor. Air connectivity, destination reputation, diaspora travel, accommodation supply and international marketing can all generate substantial demand.
The Air Journey Can Still Be The Barrier
Visa reform addresses only one part of the travel equation. IATA reports that just 19% of intra-African routes have direct flights, leaving passengers dependent on longer and often more expensive itineraries.
The organisation also identifies high operating costs as a structural aviation challenge. Fuel costs in Africa are reported at around 17% above the global average, while taxes and charges run 12–15% higher. Air-navigation charges are about 10% higher, according to IATA’s industry analysis.
| Traveller consideration | Why It Matters |
|---|---|
| Visa requirement | Determines whether advance approval is necessary |
| ETA or e-Visa | Can still create pre-departure administration |
| Direct flight | Reduces journey time and connection risk |
| Flight frequency | Determines practical flexibility |
| Airfare | Can outweigh savings from visa-free access |
| Border processing | Influences total journey time |
| Accommodation capacity | Determines whether tourism demand can scale |
This creates a more useful concept for travellers: legal accessibility is not the same as practical accessibility. A border may be open, yet a two-stop itinerary can still make a short regional trip expensive or inconvenient.
Regional Blocs Shape Traveller Movement
The divide also follows Africa’s regional architecture. Rwanda and Kenya operate within the East African Community, while Ghana and Nigeria belong to ECOWAS. South Africa and Seychelles sit within the wider Southern African regional framework, while Morocco occupies a distinct North African position.
The African Union’s Free Movement Protocol remains another major piece of the puzzle. As of July 2025, only Mali, Niger, Rwanda and São Tomé and Príncipe had ratified the protocol, although 32 states had signed it.
The gap matters because AfCFTA seeks to deepen continental trade while movement restrictions can still complicate the people-to-people element of that integration. In February 2026, the African Development Bank and African Union Commission renewed calls for visa-free movement, linking mobility with tourism, services, investment and labour movement.
What Travellers Should Check Before Booking
For travellers, the practical lesson is straightforward. A destination’s headline visa status should never be the only factor checked before booking a journey.
The safest approach is to verify the latest immigration requirement directly with the destination’s government authority. Travellers should also check passport validity, permitted stay, return-ticket rules, accommodation evidence and any digital pre-travel authorisation.
The same applies to airlines and travel advisers. A visa-free policy can change faster than printed travel guides, while airline schedules can change faster than policy reports. Checking both entry rules and flight availability is therefore essential for regional itineraries.
Africa’s Mobility Map Keeps Evolving
The continent’s travel landscape is clearly moving, but not uniformly. Rwanda remains at the most open end of the 2025 index, while Kenya has rapidly expanded access and Ghana retains a strong position. Seychelles demonstrates how digital border controls can alter statistical classifications, while Nigeria, South Africa and Morocco show that tourism performance depends on a much wider combination of factors.
The policy direction also remains active. In May 2026, the Republic of Congo announced that all African nationals will receive visa-free access from 1 January 2027, adding another significant development to the continent’s mobility debate.
For the travel industry, the bigger story is therefore not simply who requires a visa. It is whether Africa can align border access, airline connectivity, tourism infrastructure and regional integration closely enough to turn legal mobility into practical mobility. For travellers, that distinction may ultimately determine whether an apparently easy African journey is genuinely easy.
Key Data At A Glance
| Indicator | Latest figure |
|---|---|
| Intra-African travel scenarios that were visa-free in 2025 | 28.2% |
| Visa-free scenarios in 2024 | 803 |
| Visa-free scenarios in 2025 | 814 |
| African countries offering e-Visas to Africans | 31 |
| Rwanda AVOI score | 1.000 |
| Kenya AVOI score | 0.962 |
| Ghana AVOI score | 0.868 |
| South Africa AVOI score | 0.377 |
| Nigeria AVOI score | 0.321 |
| Morocco AVOI score | 0.151 |
| Seychelles AVOI score | 0.000 |
| Direct intra-African routes | 19% |
| South Africa tourists in 2024 | 8.92 million |
| Morocco tourist arrivals in 2024 | 17.4 million |
| Kenya international visitors in 2024 | 2.4 million |
| Rwanda travel-service exports in 2024 | $579.5 million |
The post Rwanda Tops Africa Visa Openness as Kenya, Ghana and Others Expand Cross-Border Tourism Access appeared first on Travel and Tour World





Comments and Responses
Please login. Only community members can comment.