
Maldives Postpones Surprising New Tax On Overseas Travel Sellers Bringing Unexpected Relief To Vacationers, Here’s The Update
-
Blogs, Travel
-
-
10 mins
-
Travel and Tour World
-
Upasana Chatterjee
-

Maldives postpones its 17% tax on overseas travel sellers to April 1, saving global travelers and agencies from immediate price hikes this winter.
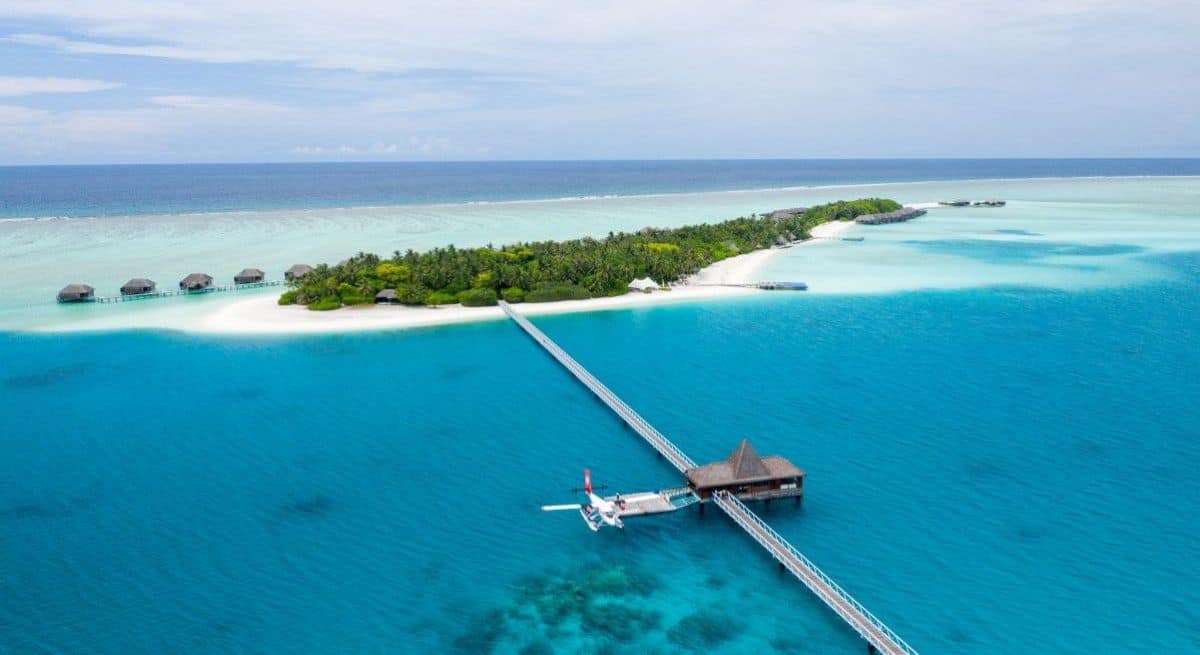
Planning a dream getaway to the Maldives has become a little easier for travelers and travel agents. I know how stressful new rules can feel. When local authorities said a 17 percent tax would apply to overseas booking sellers starting October 1 the news worried the tourism community. Families saw their vacation costs rise and travel agencies had to learn tax rules. Luckily officials, in Male decided to postpone the tax until April 1. Until then island lovers can book a winter escape without surprise price increases.
Navigating Regulatory Ambiguity and Statutory Compliance Frameworks
The initial directive from fiscal authorities in Male created immense administrative anxiety for commercial intermediaries operating across the globe. By requiring external booking platforms, tour operators, and distant reservation networks to register directly with the Maldives Inland Revenue Authority, government planners attempted to capture revenue from value generated beyond their physical borders. However, the legal mechanics of enforcing a domestic revenue mandate on foreign corporate entities triggered immediate operational complications. Industry observers noted that clear guidelines regarding liabilities, currency conversions, and statutory reporting mechanisms were severely lacking prior to the original October 1 enforcement deadline.
Without comprehensive statutory guidance, international vendors faced severe compliance challenges, leaving many unsure whether their existing contractual arrangements would trigger unexpected tax liabilities. Representatives across major commercial hubs in Europe, Asia, and North America actively lobbied for an immediate suspension or total withdrawal of the levy. They argued that imposing a 17 percent tax without adequate technical integration periods would force many platforms to pause sales for Maldives resorts altogether. The resulting decision to delay implementation until April 1 effectively prevents a dangerous disruption in booking inventory, granting statutory bodies and foreign corporate accountants essential time to iron out procedural guidelines.
Global Financial Ripple Effects on Holidaymaker Budgets and Consumer Choices
The prospective enactment of this fiscal policy carries profound long-term implications for individual consumers and family travelers planning leisure travel. If external sellers are forced to absorb a 17 percent tax levy when arranging accommodation and excursions in the Maldives, those supplementary operational expenditures will inevitably be passed directly onto end consumers. Consequently, retail prices for all-inclusive resort stays, overwater bungalow reservations, and regional transfer packages could rise noticeably once the spring deadline arrives. Such price inflation alters consumer behavior, prompting cost-conscious holidaymakers to reconsider their long-term itinerary plans or evaluate alternative tropical destinations.
Furthermore, these shifting financial dynamics could redefine competitive advantages within the global luxury tourism sector. Travelers seeking pristine beaches and high-end hospitality might divert their holiday budgets toward alternative island destinations across the Indian Ocean, Southeast Asia, or the Caribbean if external booking fees become overly punitive.
Ultimately, consumer spending patterns will pivot based on which booking channels offer the most transparent and competitive pricing structures under the prospective tax regime.
Long-Term Industry Restructuring and Strategic Adaptation for Foreign Sellers
For commercial entities that market island destinations from afar, the temporary postponement serves as a critical window to overhaul business models and tech infrastructure. The requirement to integrate directly with foreign revenue authorities introduces unprecedented compliance burdens for third-party sellers. Corporations operating out of major travel hubs in London, New York, Frankfurt, and Singapore must build dedicated accounting protocols to process the 17 percent tax correctly. Adapting software to calculate cross-border levies in real time demands significant capital investment and rigorous legal auditing to prevent double taxation or regulatory penalties.
Beyond technological overhauls, international sellers must renegotiate baseline contracts with resort owners situated across the Maldives. To maintain competitive retail pricing, foreign operators may demand lower wholesale room rates from domestic hoteliers, effectively shifting a portion of the tax burden back onto local hospitality providers. Alternatively, third-party channels may encourage travelers to book auxiliary services directly with local vendors upon arrival in Male. This strategic realignment will inevitably alter how vacation packages are constructed, priced, and distributed across global sales channels leading into the second quarter of the year.
Global Economic Outlook and Fiscal Sustainability in Island Economies
The broader economic discourse surrounding the Maldives highlights the structural vulnerabilities faced by developing island nations reliant on international visitor expenditures. Raising an estimated US$104 million through foreign vendor taxation represents a significant windfall for public infrastructure, climate adaptation initiatives, and national debt servicing. However, aggressive fiscal measures risk dampening overall visitor demand, potentially harming small-scale domestic vendors, boat captains, and local hospitality workers who rely on steady tourist arrivals. Balancing national revenue goals against private-sector market competitiveness remains a persistent challenge for economic planners in Male.
As the revised April 1 implementation date approaches, global travel markets remain on high alert for definitive legislative updates from the Maldives Inland Revenue Authority. While the short-term delay guarantees price stability for current winter bookings, long-term market confidence hinges on precise, transparent governance. International commercial enterprises, domestic hoteliers, and prospective vacationers must navigate this period of regulatory transition with heightened financial vigilance. The ultimate success or failure of this tax directive will likely serve as a benchmark for how small island economies interact with global commerce in an increasingly interconnected worldwide market.
Shift in Tourism Goods and Services Tax Baseline and Statutory Rate Escalations
In addition to the cross-border vendor mandate, the domestic fiscal framework of the Maldives underwent significant modification when the base Tourism Goods and Services Tax was escalated from 16 percent to 17 percent. This fundamental baseline shift directly impacts every luxury resort, guesthouse, and safari vessel operating across the archipelago. The internal tax rate hike serves as the foundational anchor for all secondary fiscal proposals, including the delayed levy targeting overseas intermediaries.
Understanding this statutory increase is crucial for analyzing total trip expenditure. Because domestic operators already calculate billing packages based on the elevated 17 percent baseline alongside mandatory 10 percent service charges, adding an equivalent levy onto external booking markups threatens compounding financial effects. Commercial partners across Europe and Asia argue that stacking foreign seller liabilities on top of higher domestic base taxes risks inflating final retail quotes beyond acceptable consumer thresholds.
Comprehensive Breakdown of Additional Mandatory Island Surcharges and Fees
A thorough evaluation of the luxury travel market in the Maldives requires factoring in compounding surcharges beyond baseline room tariffs. Visitors arriving via Velana International Airport in Male face an array of additional levies, including the Green Tax, which recently doubled to US$12 per person per night for resort stays. Furthermore, international departures incur combined Departure Tax and Airport Development Fees that can reach US$120 per foreign traveler in economy class.
When foreign vendor margins are subjected to an additional 17 percent tax levy, the cumulative fee structure significantly inflates total vacation budgets. For an average family visiting from North America or Europe, auxiliary taxes and mandatory fees can account for over 30 percent of total ground expenses, directly impacting length of stay and discretionary on-island spending.
Record Tourist Arrivals and Macroeconomic Revenue Benchmarks
The fiscal push by authorities in Male occurs against a backdrop of historic tourism expansion across the Maldives. Official national statistics show visitor volumes reaching an unprecedented 2.25 million international arrivals, driving national travel receipts to a record US$5.57 billion. This surging demand highlights the island nation’s immense popularity among luxury holidaymakers worldwide.
However, robust arrival metrics create a strategic dilemma for fiscal policy makers. While generating US$5.57 billion demonstrates incredible market strength, attempting to extract an extra US$104 million through foreign vendor taxation risks chilling growth. Economic analysts warn that aggressive taxation during peak performance years could encourage high-spending travelers to explore competing beach destinations across Asia and the Caribbean.
Shifting European and Asian Market Share and Source Country Vulnerabilities
Analyzing source-market data reveals distinct regional vulnerabilities to potential travel cost increases. Visitors from Europe represent the single largest geographic segment, generating over 1.33 million arrivals and accounting for nearly 60 percent of total tourist volume across the Maldives. Meanwhile, market trends show China leading individual country rankings, contributing over 329,000 annual visitors.
Because European and Asian vacationers rely heavily on tour operators and digital booking portals based in cities like London, Frankfurt, and Singapore, these source markets are uniquely exposed to foreign vendor tax policies. If external agencies pass the 17 percent tax levy onto retail package prices, long-haul traveler demand from Europe and Asia could experience price sensitivity, shifting booking preferences toward direct domestic resort channels.
Expanding Registered Bed Capacity and Resort Inventory Dynamics
To accommodate rising global demand, resort infrastructure across the Maldives expanded to 68,390 registered beds spread across luxury private islands, urban hotels, and liveaboard vessels. Managing such extensive bed capacity requires maintaining high occupancy rates year-round to ensure commercial viability for resort owners and investors.
Postponing the foreign seller tax until April 1 directly protects inventory distribution channels during the critical winter high season. Third-party travel sellers fill a massive percentage of these 68,390 beds. Imposing abrupt tax registration hurdles on foreign distributors could have led to inventory logjams, reduced resort occupancy, and lower overall yields for island hoteliers in Male and surrounding atolls.
Technical Software Integration and Accounting Compliance Overhead
Enforcing a domestic revenue mandate on foreign commercial entities presents immense technological and logistical hurdles. External booking platforms based in North America, Europe, and Asia utilize complex global distribution software that must be re-engineered to calculate, track, and remit the 17 percent tax directly to the Maldives Inland Revenue Authority.
Updating enterprise accounting software to handle cross-border tax compliance requires significant development time and financial capital. Without clear API integration standards and administrative grace periods, foreign vendors face operational bottlenecks. The postponement to April 1 provides software engineering teams and tax accountants the necessary timeline to build compliant cross-border payment architecture.
Competitive Realignment Against Regional Luxury Beach Destinations
The global luxury travel market is highly sensitive to total cost comparisons. As total holiday expenses in the Maldives increase due to baseline tax hikes, environmental surcharges, and potential vendor levies, competing tropical destinations in Asia and the Indian Ocean are positioning themselves as attractive alternatives.
Destinations such as Seychelles, Mauritius, Thailand, and Bali actively monitor price changes in the Maldives. If external package rates for Maldivian overwater villas rise significantly, price-sensitive luxury travelers may reallocate their vacation budgets to competing island markets. Maintaining competitive pricing equilibrium remains crucial for the long-term economic stability of Male.
Structural Financial Implications for Small-Scale Local Guesthouses
While luxury resorts dominate overall revenue, small-scale guesthouses on inhabited islands represent a rapidly growing segment of Maldivian tourism, generating millions of annual bednights. Unlike major international resort chains, local island guesthouses rely almost exclusively on global online booking engines and external travel sellers to attract international guests.
Imposing a 17 percent tax levy on foreign booking portals creates disproportionate friction for budget-conscious travelers seeking local island experiences. If external booking engines increase commission margins or package rates to absorb the tax, smaller guesthouses in the Maldives could suffer reduced booking volumes, directly impacting local island economies and community-based tourism initiatives.
Macroeconomic Dependency on Travel Receipts and National Debt Obligations
The aggressive push by fiscal authorities in Male to introduce new revenue measures stems from the country’s overwhelming economic reliance on the international travel sector. National financial metrics indicate that tourism travel receipts reached a landmark US$5.57 billion, serving as the primary engine for gross domestic product and foreign exchange reserves. However, this high concentration of economic activity exposes the archipelago to significant fiscal vulnerability when global shocks or trade tensions alter visitor demand.
Furthermore, public sector expenditure and external debt obligations have put substantial pressure on state coffers, compelling policy makers to seek fresh streams of tax revenue. By attempting to capture US$104 million through the 17 percent tax levy on foreign booking channels, government strategists aimed to bolster public finances without discouraging domestic investment. Delaying the mandate until April 1 underscores the delicate balance required to service sovereign debt commitments while preserving the market competitiveness of the nation’s core economic driver.
Passenger Movement Dynamics and Capacity Thresholds at Velana International Airport
Evaluating the practical application of cross-border travel taxes requires examining transit throughput at the nation’s primary gateway. Official aviation figures show that Velana International Airport in Male processed 8.28 million total passenger movements in a single year, reflecting a robust 7 percent annual growth rate. This traffic included over 5.38 million international terminal passengers and 1.73 million seaplane transfers connecting tourists directly to outlying private island resorts.
These dense passenger volumes illustrate why tracking and taxing external booking sources poses such complex administrative challenges. When foreign booking channels handle millions of international arrivals passing through Velana International Airport, requiring third-party agencies across Europe, Asia, and North America to integrate directly with local tax software requires extensive operational synchronization.
Surge in Annual Overnight Stays and Evolving Length of Stay Metrics
A critical benchmark for measuring overall market performance is the volume of registered overnight stays generated across the island nation. Annual tourism reports record an extraordinary 13.69 million total bednights across luxury private resorts, urban transit hotels, and local island guesthouses. Visitors maintained an average stay duration of 7 full days, keeping accommodation facilities operating at high capacity throughout the primary travel seasons.
This sustained demand in total bednights explains why foreign travel vendors play such a decisive role in inventory management. External booking engines and international wholesalers funnel millions of these 13.69 million bednights into local resorts. If the government had proceeded with the original October 1 tax deadline without resolving technical ambiguities, third-party distributors might have restricted room inventory, threatening occupancy rates and overall room yield during the crucial winter travel period.
Disproportionate Tax Burdens Across Resort Villas versus Local Island Guesthouses
The prospective imposition of a 17 percent tax on external booking intermediaries creates distinctly different financial pressures depending on the accommodation model. Luxury resorts recorded 10.9 million bednights, catering primarily to high-net-worth foreign vacationers who display lower price sensitivity to additional surcharges. In contrast, local island guesthouses generated 2.21 million bednights, serving budget-conscious travelers seeking culturally immersive experiences on inhabited islands.
Because independent guesthouses lack the massive marketing budgets of international resort conglomerates, they rely almost entirely on third-party online booking engines based in Europe and Asia to attract guests. Applying a blanket 17 percent tax levy on foreign vendor markups threatens to disproportionately squeeze profit margins for these smaller, community-focused operators. Consequently, delaying policy implementation until April 1 grants local island entrepreneurs essential breathing room to adjust retail pricing and protect their market share.
Foreign Exchange Liquidity and Banking Integration Challenges for External Vendors
Beyond basic tax registration, enforcing a cross-border levy involves complex currency conversions and central bank regulations governing foreign exchange transactions. The Maldives Inland Revenue Authority requires tax liabilities to be calculated, reported, and remitted according to strict statutory guidelines, creating compliance hurdles for foreign vendors operating in foreign currencies like the Euro, British Pound, or US Dollar.
International booking platforms processing payments across London, Frankfurt, New York, and Singapore face operational friction when converting retail transactions into local settlement currencies. Without established central bank clearing pathways and clear foreign exchange protocols, external agencies risk exposure to exchange rate volatility and banking transfer fees. Pushing the enforcement timeline back to April 1 allows financial regulators in Male to coordinate with international banking institutions, ensuring seamless cross-border tax remittance once the policy officially takes effect.
The Final Horizon
At its core travel is not about spreadsheets, tax codes or government revenue. Travel is about the magic of escaping to paradise. When news broke that this steep tax was put on hold a collective sigh of relief echoed from family dining tables that were planning years getaway. Small boutique resort owners were eagerly waiting to welcome guests. Though April 1 may eventually bring changes this brief pause keeps the door open, to memories. Travel proves that in complex economics keeping world-class travel welcoming, accessible and deeply human remains the ultimate destination.
The post Maldives Postpones Surprising New Tax On Overseas Travel Sellers Bringing Unexpected Relief To Vacationers, Here’s The Update appeared first on Travel and Tour World





Comments and Responses
Please login. Only community members can comment.